
Santander’s Higher Brazil Exchange Ratio Still Moves With the Shares
Santander improved the share terms for the minority stake in its Brazilian unit. The number of shares and their market value answer different questions for holders on either side.
Inside this article
01The revision changes the quantity of consideration ↓02Compare the ratio and the share price on the same basis ↓03Dividends change the displayed ratios ↓Event / source date: 12 November 2026 — Banco Santander announced improved terms for its intended Santander Brasil exchange offer. · Published 13 NOVEMBER 2026
The revision changes the quantity of consideration
Banco Santander improved the terms of its intended offer for the approximately 10% of Santander Brasil it does not already own. The proposal, announced on 12 November, increases the exchange ratio by 5%. Before specified dividend and other adjustments, it would give a holder 0.4260 newly issued Banco Santander shares for each Santander Brasil unit or American depositary share, up from 0.4056 in the July announcement. For each common or preferred share, the published unadjusted ratio rose from 0.2028 to 0.2130.
The parent says it intends to launch concurrent exchange offers in Brazil and the United States. The exchange would move participating holders from a security in the Brazilian subsidiary to one representing an interest in the parent. Santander says the consideration would continue to be delivered through Brazilian depositary receipts or American depositary shares, as applicable, tradable in São Paulo or New York respectively.
There are three separate items to read in the announcement: how much parent equity a holder would receive, what that equity is worth at a given time, and whether the offer proceeds. Only the first of those has been directly changed by the new ratio.
Compare the ratio and the share price on the same basis
A useful valuation comparison starts by choosing the security involved and the time at which both market prices are observed. A Santander Brasil unit combines a common and a preferred share. If the calculation starts with a unit, it needs the ratio for a unit. Applying the common-share ratio to the unit would halve the quantity of consideration before any question about the market prices arose.
Consider a hypothetical example that omits exchange rates and receipt conversion because both sides are already expressed in the same currency per equivalent security. If one parent share is worth 10 currency units, a ratio of 0.4260 represents 4.26 per subsidiary unit. At a parent share price of 9.50, the same ratio represents approximately 4.05. That arithmetic illustrates why a higher ratio offers more parent shares while the implied value still changes with the parent share price.
A percentage premium requires another input, the comparison price for the security being exchanged. Change its date or choose a different security and the premium can change. The company’s approximately €1.9 billion maximum consideration is based on the previous closing market price and full acceptance. The stated value therefore describes a calculation under assumptions. It is not a fixed cash amount payable on every settlement date.
Dividends change the displayed ratios
The company presented both headline terms and a set of dividend-adjusted numbers. After accounting for dividends already paid by both banks since 30 July, Santander stated that the ratios as of 12 November would be 0.4246 per unit or American depositary share, 0.2124 per common share and 0.2122 per preferred share. Different adjustments help explain why a published common-share number and a published preferred-share number can differ even though the headline ratios match.
A holder comparing two announcements needs to keep the adjustment convention consistent. A July ratio before dividends and a November ratio after dividends contain more than the change in the offer’s headline terms. Marking the comparison date and identifying which distributions are included makes that distinction visible. Subsequent events covered by the terms can affect the ratio before the offer expires.
The proposed exchange also changes what the holder is exposed to. The subsidiary security is tied directly to the Brazilian business. The parent security represents a share in the wider group, which includes Brazil alongside other operations. Evaluating the two positions therefore requires more than comparing the first available premium. The interest received after the exchange would have a different earnings base and market price.
The conditions still govern the transaction
Santander says full acceptance would involve issuing approximately 166 million parent shares, about 1.1% of its current share capital. It plans to seek approval for the corresponding capital increases at an extraordinary meeting expected on 15 December. The commencement and terms also remain subject to relevant regulatory approvals and other conditions described in the announcement.
The company projects an increase in earnings per share of about 0.3% from 2029 and in tangible book value per share of approximately 0.6%. Those are management estimates based on current expectations. They depend on the effect of acquiring the remaining interest and on how the share count shapes earnings per share. No future operating outcome was observed on 12 November.
A clear reading of the revised offer keeps the items in their proper order. First identify the instrument and the applicable ratio. Then translate the consideration into a market value on a consistent basis. Finally check approvals and terms as they stand at the decision date. The 5% increase is real as an improvement in the published ratio. The shareholder still needs to follow what that ratio buys and whether the proposed exchange becomes available. Both sets of shareholders will eventually be able to compare the outcome with the original terms by observing how many securities were tendered, what consideration was issued and which conditions the parties reported as satisfied.
Gabriel Nicolaev — CyGuru
Sources & further reading
Banco Santander · Revised Santander Brasil offer terms ↗
Banco Santander · 12 November communication filed with Spain’s CNMV ↗
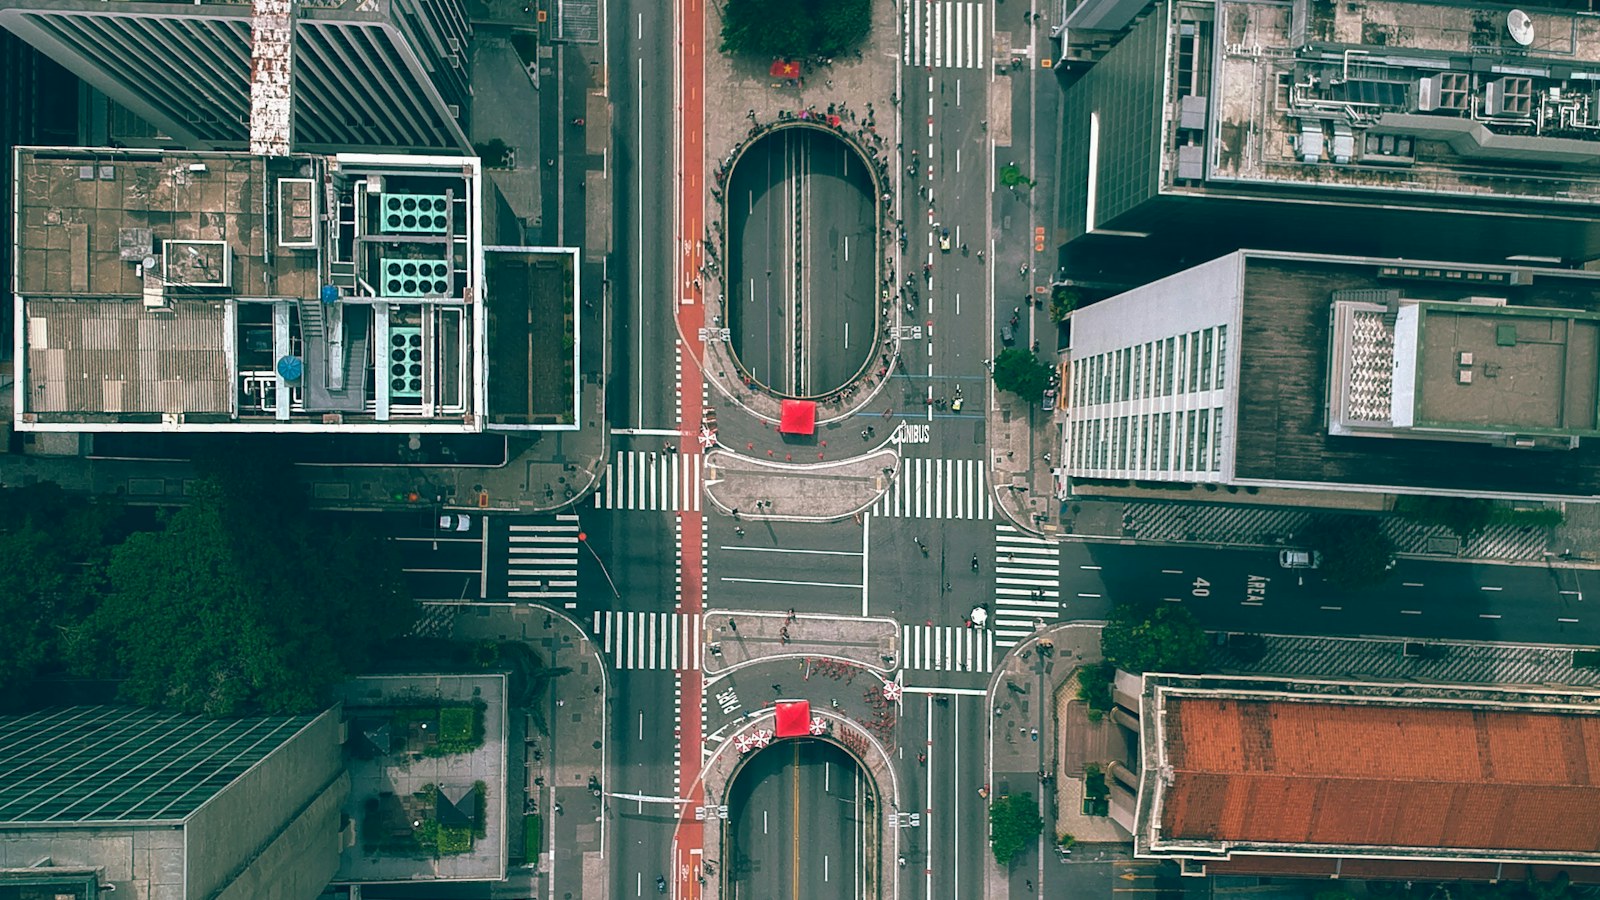
Avenida Paulista in São Paulo illustrates the Brazilian market. Photo by Gabriel Ramos on Unsplash.
Another angle on this subject
Continue through related ideas, decisions and consequences.
 Money & Business
Onex’s Fundraising Milestone Still Has to Travel Through the Cost Base
A first fund close and fee earnings answer different questions. Onex’s latest release shows why readers should keep the layers separate.
 Technology & AI
An AI Energy Claim Is Only as Clear as Its Measurement Boundary
Energy per request, total electricity demand and avoided emissions answer different questions. Comparing them requires visible assumptions and a defined useful output.
 Money & Business
An Adaptation Bond Is Not an Insurance Policy
IFAD’s new rural adaptation bond connects a capital-market instrument with a resilience purpose. The investor relationship and the protection promised to communities require different questions.