
Bavarian Nordic’s Travel Growth Meets a Different Procurement Clock
Bavarian Nordic’s latest results show why travel-health sales and public-preparedness orders need separate operating and financial interpretations.
Inside this article
01A nearly flat total can conceal a major shift ↓02Purchasing purpose affects the revenue calendar ↓03Why adjusted growth needs its own label ↓Event / source date: 13 November 2026 — company results announcement. · Published 14 NOVEMBER 2026
A nearly flat total can conceal a major shift
Bavarian Nordic’s November 13 results describe two businesses moving at different speeds. Third-quarter revenue was DKK 1,805 million, close to DKK 1,795 million a year earlier. Inside that total, Travel Health revenue grew 22%. Across the first nine months, the company reported Travel Health growth alongside a 20% decline in Public Preparedness revenue, which it described as consistent with expectations.
Those figures invite a more useful question than whether the headline grew enough. What kind of demand is generating the revenue, and on what timetable does it arrive? Sales associated with travel health and government preparedness can share manufacturing capabilities while following different purchasing decisions. Treating the combined total as one continuous demand curve risks hiding that distinction.
Purchasing purpose affects the revenue calendar
A government buying preparedness supplies is making a decision about capacity available for a future need. The commercial sequence may include a budget, an agreement, delivery requirements and acceptance. Revenue can be concentrated around stages in that sequence. A lower period does not automatically establish that preparedness has become less important or that the underlying capability has lost value.
Travel-related demand has a different route to the manufacturer. A person preparing for travel may interact with a clinic or another healthcare provider, while orders move through distribution channels. Product sales and end-user activity are connected, but they are not identical observations. A shipment to a channel is not itself proof that every unit has been used.
This distinction is an analytical framework for interpreting the reported segments. It does not establish the timing of any undisclosed contract or the stock level of any distributor. Those would require specific evidence beyond the headline release.
Why adjusted growth needs its own label
The company reported Travel Health growth of 22%, or 32% after adjusting for discontinued partnerships. Both measures can be useful if they are kept separate. The reported figure describes the business as recorded. The adjusted comparison attempts to make the continuing activities more comparable across periods.
The difference should prompt a question about the comparison base rather than a choice of whichever number looks more attractive. What revenue was present before but is no longer part of the comparison? What costs left with it? Does the adjusted growth rate help explain current operations without obscuring the actual size of the business?
A hypothetical supplier that ends a distribution partnership might show weak total growth while its retained products gain customers. Conversely, a strong retained-product comparison might coexist with lower absolute revenue after the partnership ends. Neither observation cancels the other. An assessment of business quality needs the bridge between them.
Manufacturing capacity has to serve both patterns
Different order rhythms create a planning challenge. Capacity committed to one product or customer may not be instantly available to another. Production scheduling, release processes, inventory and delivery obligations all influence the practical flexibility of the operation. A revenue mix shift can therefore affect the factory before it becomes visible in the consolidated result.
Imagine a manufacturer planning a period with a large scheduled institutional delivery and regular commercial demand. It needs to protect the delivery commitment while avoiding unnecessary stock in the commercial channel. If the institutional timetable changes, the factory may face a different balance of inventory and available production slots. The appropriate response depends on the contract and product, not a general assumption that all unused capacity can be redeployed.
CYPAPER’s customer-concentration analysis emphasizes how customer calendars shape business exposure. The same reasoning applies here at the segment level. It is the combination of commitments, timing and flexibility that determines how smoothly a revenue base can be served.
Margins should be compared on consistent terms
Bavarian Nordic reported a strong third-quarter EBITDA margin and maintained full-year guidance. Its presentation also identifies a prior-year comparison issue: a voucher sale contributed other operating income in 2025. A reader comparing profitability across years needs to preserve that qualification rather than mistake a special item for ordinary product earnings.
The practical task is to separate recurring product contribution, period-specific items and planned investment. Management attributes the current gross-margin performance to a favorable product and market mix. That is the company's explanation; it should be tested against future segment results rather than assumed to be a permanent property of the business.
A strong quarter can coexist with a lower expected annual margin if the remaining period has a different mix or investment profile. The full-year outlook is a forecast, not a result already earned. The next releases will show how closely the planned pattern matches actual deliveries and costs.
What the next useful evidence would look like
For readers following the business, the important evidence is a consistent explanation of segment demand and its conversion into revenue and cash. Do institutional deliveries occur when expected? Does Travel Health growth persist without relying on the same comparison adjustments? Does inventory remain proportionate to the commitments it supports?
CYPAPER’s cash-buffer analysis offers another lens: funding requirements can arrive before a reported sale. A company with different customer calendars needs enough flexibility to finance that interval. Revenue visibility and available cash should therefore be considered together, without treating one as a substitute for the other.
The November announcement demonstrates why a nearly unchanged total should not end the analysis. Beneath it are distinct demand patterns, comparison effects and production decisions. Understanding those patterns is more informative than forcing every segment into a single growth story.
Gabriel Nicolaev — CyGuru
Sources & further reading
Bavarian Nordic — Third Quarter 2026 Results (company release via GlobeNewswire/Ritzau) ↗
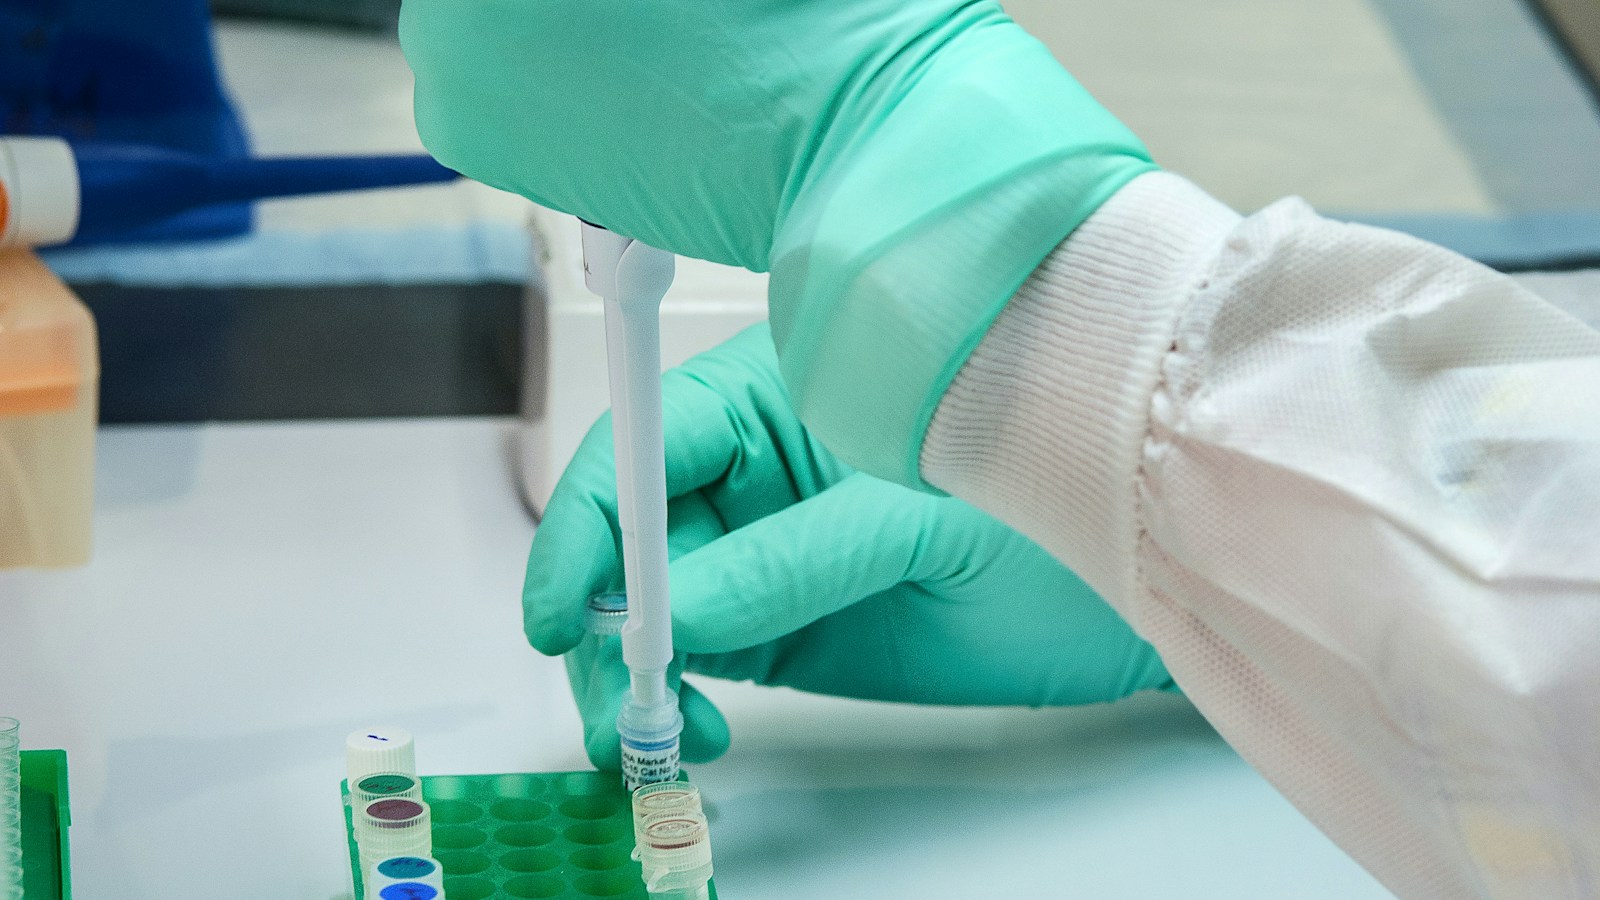
Illustrative laboratory photograph by CDC on Unsplash; not a Bavarian Nordic facility.
Another angle on this subject
Continue through related ideas, decisions and consequences.
 Money & Business
Onex’s Fundraising Milestone Still Has to Travel Through the Cost Base
A first fund close and fee earnings answer different questions. Onex’s latest release shows why readers should keep the layers separate.
 Money & Business
Cineverse’s Bigger Revenue Base Requires a New Margin Comparison
Cineverse’s November results reflect an acquired technology business mix. Revenue growth, operating margin and acquisition accounting tell different stories.
 Money & Business
Northview’s FFO Growth Has Two Engines: Properties and Financing
The REIT’s latest results put rent, occupancy and interest savings in the same headline. Each needs its own comparison.